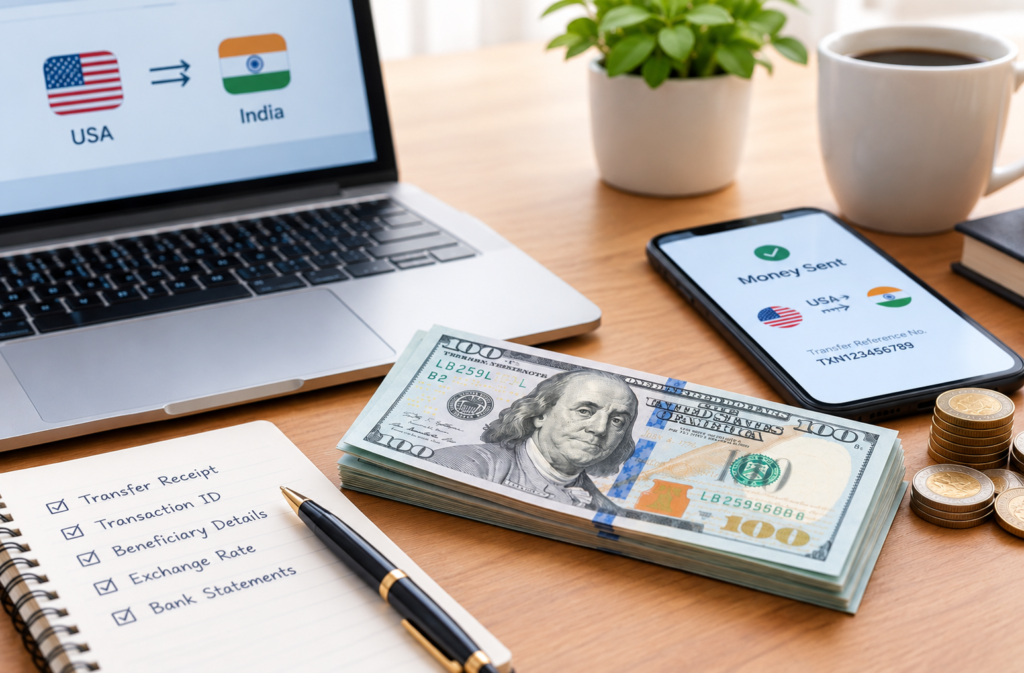
You send money from the USA to India and the transfer goes through without any immediate issue. Months later, your bank, tax adviser, or another financial institution asks you to explain the transaction. Without the original receipt, bank statement, or supporting documents, proving exactly what happened can become much harder.
Keeping proper records gives both the sender and recipient a clear trail of the transaction. It can help establish the amount sent, source of funds, purpose of the payment, exchange rate used, and details of the beneficiary.
For regular USA-to-India remittances, organized documentation also makes it easier to respond to compliance or tax-related questions. It supports transparency without creating unnecessary confusion.
Essential Documents to Save for USA-to-India Transfers
The records you need depend on the nature and value of the transaction. For most transfers, however, it is sensible to maintain a complete digital record from the moment the payment is initiated until the recipient confirms the funds have been received.
Transaction Statements & Bank Payment Receipts
Start with the basic transaction records. Save the transfer confirmation, electronic receipt, remittance advice, and the relevant bank statement showing the debit from the sender’s account.
These records should ideally show the transaction date, amount, currency, recipient information, transaction or reference number, and applicable fees. If currency conversion is involved, retain information showing the exchange rate or converted amount provided by the transfer service.
Your US bank statement can establish that the funds left your account. The transfer receipt can provide additional details about where the money was intended to go.
Keeping both records together creates a much clearer transaction trail than relying on either document alone.
Purpose Codes and Foreign Inward Remittance Certificates (FIRC)
The purpose of a remittance can be relevant to how an Indian bank records and processes an incoming transaction. Depending on the transfer, the sender may need to provide or select an appropriate purpose classification, such as family maintenance, gift, or another legitimate purpose.
Keep a record of the purpose stated when the transfer was initiated. If the Indian receiving bank provides a Foreign Inward Remittance Certificate, bank advice, or another formal confirmation of the inward remittance, retain that document as well.
An FIRC is not automatically issued for every ordinary remittance. Its availability and format depend on the transaction and the receiving bank. In some cases, a bank credit advice or other remittance confirmation may be the relevant record.
If you are sending money to family in India, it is also useful to understand the tax treatment of gifts and when additional documentation may be appropriate. The Is Money Sent From the USA to Family in India Taxable? guide can provide useful context before you organize your records.
Gift Deeds & Family Relationship Documentation
Large transfers made as genuine gifts may require more supporting documentation, depending on the circumstances. If a formal Gift Deed is prepared, retain a signed copy along with evidence showing the relationship between the donor and recipient where relevant.
Do not assume that every family remittance requires a Gift Deed. The appropriate documentation depends on the nature of the transaction, the amount involved, the relationship between the parties, and applicable tax rules.
The purpose of maintaining these records is to establish what the payment represented. A clear record can help distinguish a genuine gift from a loan, business payment, investment, or another type of transaction.
Identification Records for Non-Bank & Alternate Payouts
Not every recipient receives money through a conventional bank account. Some authorized remittance services may offer cash pickup or other eligible payout methods.
For these transactions, retain the transfer receipt, transaction reference and collection receipt. Where appropriate and legally permissible, keep a record of the identification used by the recipient.
If someone in India receives money without a traditional bank account, understanding the documentation involved becomes particularly important. The Can You Send Money to India Without Having an Indian Bank Account? guide explains the considerations around alternate payout methods.
How Record-Keeping Prevents Bank Holds and Rejections
Good documentation can make it easier to respond when an Indian bank or transfer provider requests additional information.
For example, a compliance team may want to understand the source of funds, relationship between sender and recipient, or purpose of the transaction. Having the original receipt, bank statement and relevant supporting documents allows you to provide consistent information.
Your records should also match the details entered during the transfer. Differences in names, account numbers, transaction amounts, or stated purposes can create additional questions.
Record keeping does not guarantee that a transaction will never be held or rejected. It does, however, give you evidence to help resolve questions efficiently.
For a broader understanding of why an Indian bank may hold, reject, or return an incoming remittance, you can refer to the Can an Indian Bank Reject Money Sent From the USA? guide.
Managing Records Across Bank Holidays & Processing Cycles
The date shown on your US bank statement may not always be the same as the date on which an Indian bank posts the incoming credit.
Bank holidays, weekends, and local processing schedules can create differences between the date a transfer is initiated, the date funds leave the sender’s account, and the date the receiving bank records the credit.
This is why keeping timestamped transaction confirmations is useful. Save the original receipt rather than relying only on the date displayed in an app later.
If you maintain records for tax or accounting purposes, record the relevant transaction dates accurately instead of assuming that the US debit date and Indian credit date will always be identical.
Understanding how holidays can affect banking schedules can also help you interpret transaction records correctly. The [Can a USA-to-India Transfer Be Sent on a Bank Holiday in India?] guide provides additional context.
Recommended Retention Periods & Digital Archiving Best Practices
There is no single universal retention period that applies to every USA-to-India remittance. The appropriate period can depend on the purpose of the payment, tax requirements, applicable jurisdiction, and whether the transaction may be relevant to a future inquiry.
For US tax records, the IRS generally recommends keeping records for as long as they may be relevant to the administration of tax law. The commonly used baseline is three years for many returns, while certain circumstances can require longer retention.
Indian tax documentation may also need to be retained for longer periods depending on the transaction and applicable assessment or reassessment rules. Rather than relying on a fixed “six to ten years” rule for every remittance, keep significant transaction records for a period that covers the relevant legal and tax requirements.
For digital storage, create a dedicated folder for USA-to-India transfers. Keep receipts, bank statements, supporting documents, and correspondence together. Use secure cloud storage or an encrypted digital archive and maintain a backup.
Frequently Asked Questions (FAQs)
How long should I keep records of money sent to India from the USA?
Keep records for as long as they may be relevant to your US or Indian tax, banking, or legal obligations. Three years is a common IRS recordkeeping benchmark for many tax matters, but specific circumstances can require longer retention. Significant transactions should generally be retained conservatively.
What is a Foreign Inward Remittance Certificate (FIRC) and why is it important?
An FIRC is a document that can provide formal evidence of an inward foreign remittance received through an authorized Indian banking channel. However, it is not automatically issued for every remittance. Depending on the transaction, a bank advice or other inward remittance confirmation may be provided instead.
How does proper record keeping ensure my transfers are safe and compliant?
Records create a clear trail showing who sent the money, how much was sent, where it was intended to go, and the stated purpose. This can help with compliance reviews, tax questions, disputes, or requests for proof of funds.
It also helps demonstrate transparency when using a trusted service for USA-to-India transfers.
Conclusion & Strategic Summary
Keeping organized records is an important part of managing money sent from the USA to India. Save transfer receipts, bank statements, transaction references, purpose information, and relevant supporting documents.
For certain transactions, additional records such as Gift Deeds, bank advice, or FIRC documentation may also be useful. Good record keeping can make tax and compliance questions easier to address while giving both sender and recipient greater transparency.
When you send money from the USA to India with Abound, maintaining your own transaction records alongside the transfer information helps you stay organized and prepared.